


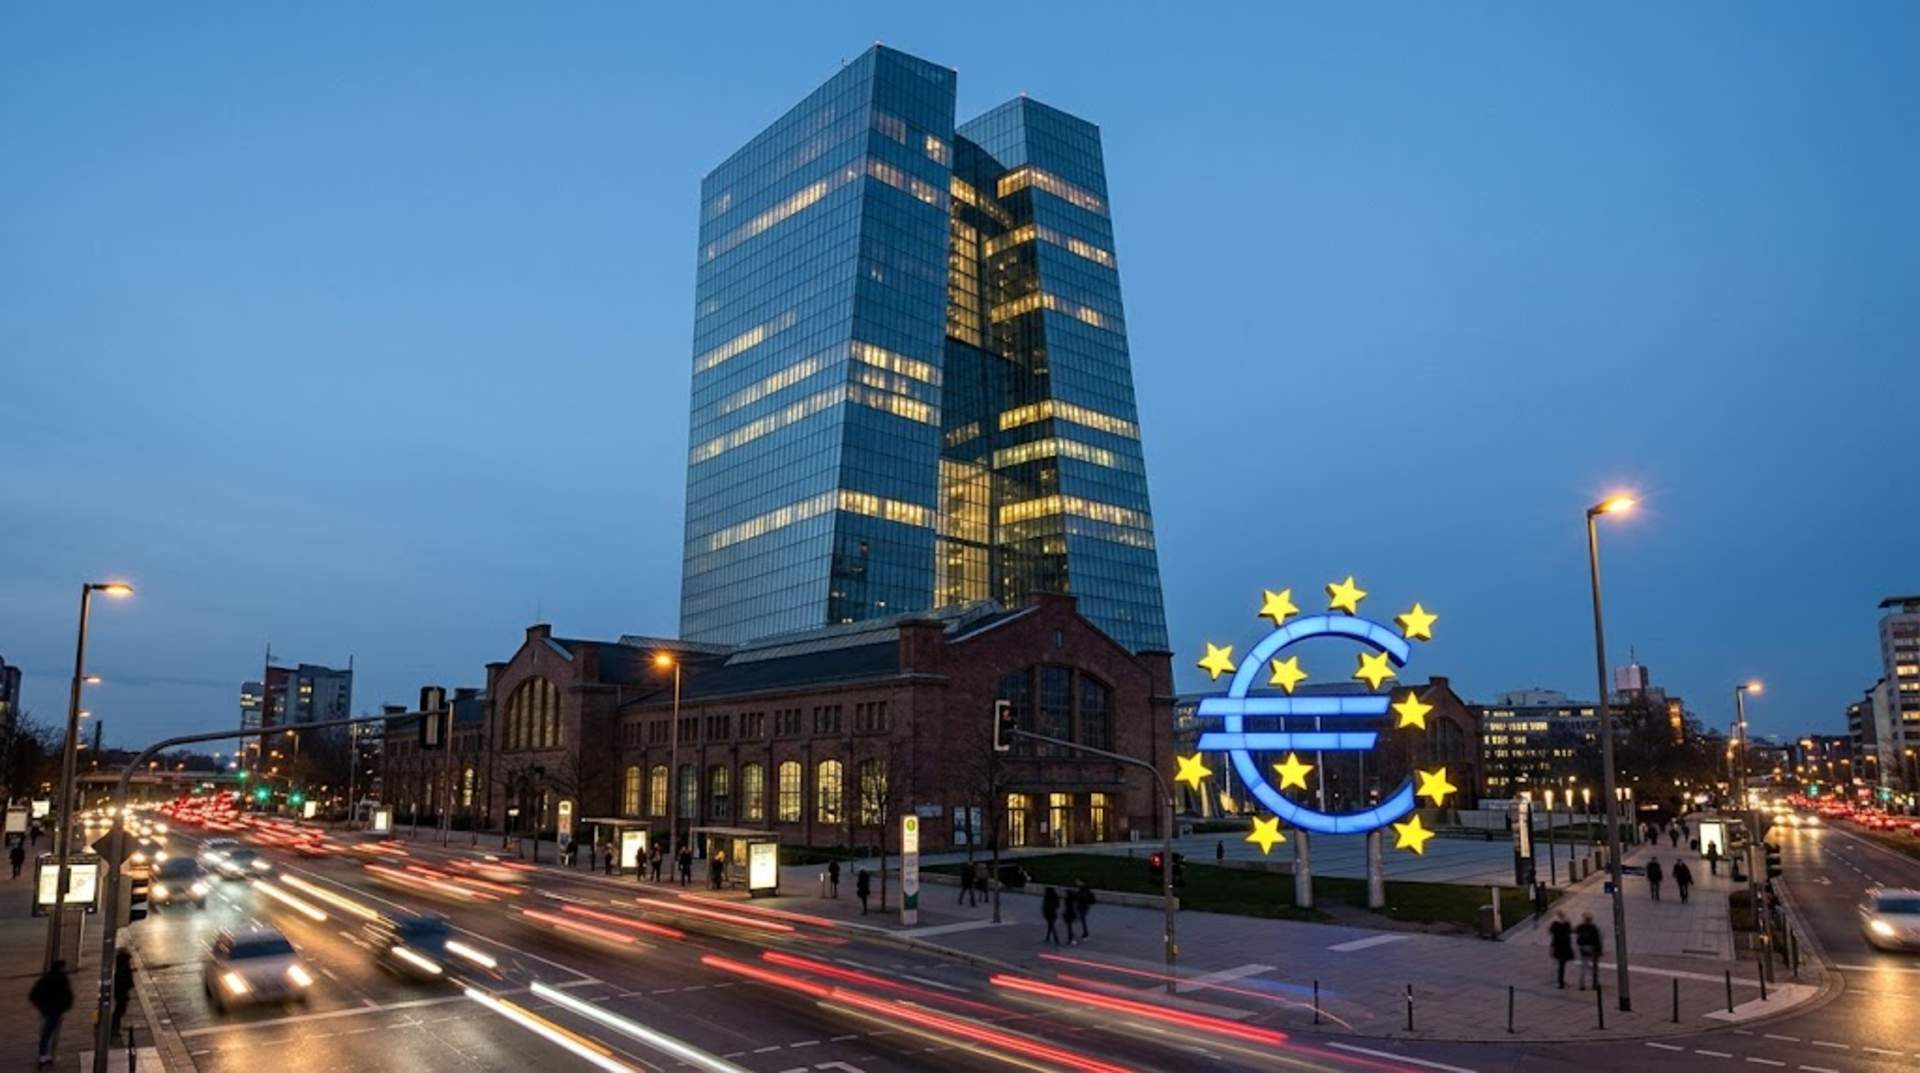
A widely anticipated European Central Bank rate cut delivered a 25-basis-point reduction to Eurozone borrowing costs on Wednesday, shifting the region's monetary focus from fighting inflation to rescuing a stalling German industrial sector.
Meeting at their Frankfurt headquarters, the ECB Governing Council officially lowered the benchmark deposit facility rate to 2.25 percent. The decision marks the third consecutive quarterly reduction in 2026, unwinding the aggressive monetary tightening cycle that defined the past three years. ECB President Christine Lagarde cited a rapid cooling of consumer prices across the 20-nation currency bloc alongside alarming contractions in manufacturing output as the primary drivers for the policy easing.
According to September 2026 flash estimate data from Eurostat, Eurozone headline inflation dropped to 1.8 percent, moving safely below the central bank's long-standing 2 percent target for the first time in nearly five years. This milestone provided policymakers with the necessary mathematical justification to act. However, core inflation, which strips out volatile energy and food prices, remains slightly elevated due to persistent wage growth in the services sector, prompting the council to reiterate that future rate decisions will remain strictly data-dependent.
The German Industrial Drag
While falling inflation provided the permission to cut rates, a deepening economic crisis in Germany provided the urgency. Germany remains the primary anchor pulling European economic growth downward. The continent's largest economy has faced four consecutive quarters of stagnant or negative growth, dragging down the aggregate performance of the entire Eurozone.
Major German automakers and heavy machinery manufacturers are currently struggling with permanent structural shifts rather than temporary cyclical dips. These industries face fierce competition from Chinese electric vehicle exports and industrial energy costs that remain structurally elevated compared to pre-2022 levels. The loss of cheap Russian pipeline gas continues to squeeze the margins of chemical producers and heavy manufacturers, leading to a visible deindustrialization trend in the country's industrial heartlands.
During the post-meeting press conference, Lagarde acknowledged that domestic consumer demand across the Eurozone is simply too weak to offset the slump in industrial exports. Financial Times analysts noted that several prominent German industrial conglomerates have begun warning of rare domestic plant closures and large-scale workforce reductions heading into the winter of 2026. Lowering the cost of capital through Wednesday's rate cut is widely seen as an emergency measure to stimulate corporate reinvestment and prevent a deeper manufacturing recession from spilling over into the broader European labor market.
Diverging Global Monetary Paths
The latest easing cycle puts Frankfurt on a diverging path from other major central banking institutions around the world. While the United States Federal Reserve has held its own interest rates steady through late 2026 to manage domestic labor market heat and sticky core inflation, European officials are now openly prioritizing recession prevention over strict price containment.
This transatlantic divergence immediately impacted global currency markets. The euro depreciated slightly against the dollar in Wednesday afternoon trading, falling to a multi-month low as investors priced in the widening interest rate gap between US and European debt instruments. A weaker euro, however, is not entirely unwelcome in Frankfurt; it makes European manufactured exports more competitive on the global market, providing a much-needed tailwind for struggling German factories.
European equities rallied on the prospect of cheaper corporate debt refinancing. For international trade hubs and global supply chains, consistently lower European borrowing costs could eventually help stimulate business investment and consumer demand for imported manufactured goods heading into 2027. However, economists warn that monetary policy alone cannot fix the structural competitiveness issues currently plaguing Europe's largest industrial base.
Comments
0